News
Keeping you up to date on news, events and what’s happening at ESG…

Keeping you up to date on news, events and what’s happening at ESG…
By Jo Knight, Chief Marketing Officer, ESG
The UK energy market is entering its next phase. Technology, regulation, flexibility and customer expectations are all shifting at once, creating opportunities and complications in equal measure.
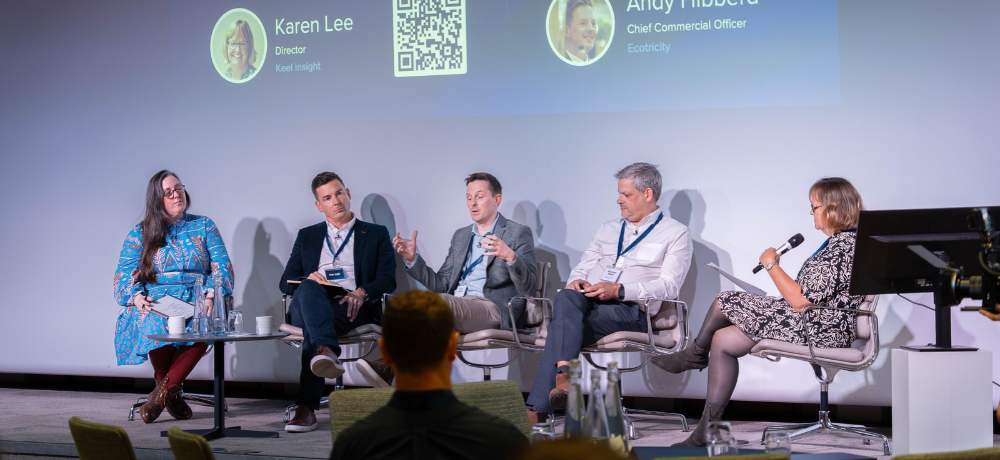
At the Smarter Energy Insights Forum 2026, the closing panel tackled a deceptively simple question: what will distinguish a market-leading energy retailer by 2030, whether or not Clean Power 2030 is delivered on schedule?
The answers, from independent advisor Kate Mulvany, Chris Russell of Baringa, Andy Hibberd of Ecotricity, and Royston Black of Engage Consulting, were refreshingly practical. Here are the themes that stood out.
It might not be glamorous, but the panel was united on one point: the fundamentals decide who thrives.
In the current wholesale environment, Chris Russell argued, suppliers need “brutal efficiency” involving:-
• a relentless focus on data.
• end-to-end commercial outturn.
• customer service.
Margins are tight and volatility has been punishing, so a strong foundation matters more than any single new initiative.
Royston Black added that clear communication is just as vital. Where customers are on time-varying or implicit flexibility models, retailers should show the savings they’re receiving compared with what they would otherwise have paid. If the benefits stay hidden in the background, customers have little reason to trust them.
A large share of both household and business customers simply want things to work. For them, the priority is less about communication and more about transparency and billing accuracy.
Black also highlighted a practical risk that is easy to overlook. If new propositions rely on real-time meter data, a failing meter that takes six months to fix under a standard contract will undermine the customer experience and the proposition itself.
Data and metering contracts need to be fit for the services retailers want to offer, and the target operating model must be designed around them.
Andy Hibberd described a market that’s moved on from the days when everyone simply received a bill. Today there’s a spectrum, from highly engaged and knowledgeable customers to those who, as he put it, don’t want to think about energy at all.
It’s the retailer’s job to do the thinking for them, and success in 2030 will require serving that whole range.
Personalisation is relevant up to a point, but the panel favoured simplicity. Rather than millions of bespoke offers, Russell suggested a manageable set of archetypes, perhaps ten or twelve, defined by factors such as asset ownership or shared properties, and executed well.
Hibberd agreed: customers weigh price, service, mission and their own energy journey differently, and grouping them into pots makes messaging simpler and trust easier to build.
The same discipline applies to non-domestic supply. Is the proposition front-of-meter or behind-the-meter? Is it bundled with assets, a pure service, or focused on price?
Taking a whole-service approach, helping a business cut consumption, changes the commercial model entirely. Each route has different economics, and smaller and larger suppliers alike need to be clear about the outcome they’re pursuing.
Asked whether a strong brand and mission deliver measurable commercial advantage, Hibberd rejected the either-or. With cost-of-living pressures weighing on households and manufacturers alike, price is paramount for many customers right now.
But as cost becomes less of a barrier, differentiators such as brand and values will matter more. The two are intertwined.
Kate Mulvany offered a candid reality check. Higher and more volatile energy prices are likely to dominate for the rest of the decade, and political volatility, domestic and international, is not about to subside.
Non-domestic customers are doubly exposed, while household affordability pressures aren’t going away either.
Retailers that thrive will be those that juggle these competing demands, build trust, stay transparent and keep costs down, while recognising they are not miracle workers.
The past few years have brought incremental change, but Mulvaney urged the industry to prepare for step changes too. She pointed to the possibility of more localised political intervention, such as regional incentives or redistributed network charges, as well as more dramatic scenarios, from new taxes on renewable assets to a shift in European politics that could disturb interconnector arrangements.
Too many organisations treat very plausible events as unforeseeable. Her advice: keep the capacity to react quickly to things that can’t be predicted in detail.
Black grounded this in recent experience. This summer, some European nuclear plants had to curtail output because of water shortages. Less generation abroad means less available through interconnectors and higher prices at home, something he considers highly likely to recur over the next five to ten years.
Moderator Karen Lee challenged the room on whether the flexibility journey is genuinely consumer-led or still shaped primarily by what the industry and system need. Many households lack roof space for solar, room for a battery or a driveway for an EV. Lee’s own planning restrictions on solar panels illustrated the point neatly.
Mulvany offered a reassuring perspective. Because the aim is to avoid the expensive peak, only a relatively small proportion of customers need to shift load or use storage for bills to fall for everyone, largely through deferred network costs and lower wholesale-related costs.
It may not feel fair, particularly when early adopters have benefited from subsidised technology, but modelling suggests the system-wide gains are real. Another panellist agreed that fairness can be politicised, and that progress should be made where it is easiest, rather than waiting for perfect equity.
Black noted that houses in multiple occupation and tenanted properties remain a particular challenge. Encouragingly, new batteries can now be fitted in far more settings, including social housing, and trials with councils in Oxfordshire are showing local-scale benefits for people who would normally be shut out.
Black also argued that debt too often feels like a problem the industry hopes will disappear. He suggested investing now, in batteries and in time-of-use and type-of-use tariffs, to help customers keep warm when it matters while limiting unnecessary consumption. That would be a far better outcome than the stark choice prepayment can impose, where customers are either supplied or cut off.
Lee closed by asking each panellist for the one tough investment retailers should make now, even if returns are slow to appear.
Operational excellence
Hibberd chose something that is anything but flashy: continually evolving operational excellence. With market-wide half-hourly settlement bringing vastly more data, retailers will need data lakes, new ways of accessing information, and updated processes, controls and governance to protect both customers and the business.
Russell agreed, adding that historically siloed, function-by-function processes need to become integrated end to end, with margin visibility far closer to real time. His warning was to start any data strategy by deciding what you will do with the output, and how it will reach service, operations and commercial teams, rather than accumulating new reports and tools that no one acts upon.
For those targeting value-based business propositions rather than simple price, Russell noted that asset investments are illiquid and have long paybacks. Programmes discussed during the day may bring more certainty over returns, but decisions will need to be made sooner rather than later.
Mulvany stressed that debt in the domestic market largely reflects genuine inability to pay, and that every solution carries consequences, including how other customers perceive it. Inaction is also a decision, and an unhelpful one. Retailers should be open about the trade-offs and make sure Ofgem receives clear steer and guidance, or risk further eroding public trust in the industry.
Black added a final, pragmatic point. Not every organisation can field a team of specialists at every industry meeting, but every organisation needs a strategy for tracking and responding to the substantial change in the pipeline, because it will affect them.
The panel’s closing discussion turned to AI. Russell and Hibberd both urged caution over terminology. Getting data right, traditional machine learning, and process automation are often conflated with AI.
Hibberd estimated that around 90% of what retailers need is process automation and optimisation, with perhaps 10% genuinely AI. Russell suggested practical near-term wins lie in giving customers and service agents better tools to surface knowledge and insight, rather than handing over decision-making.
Mulvany added a point worth remembering: your customers are already using AI. Whatever appears on your website or in your communications is likely being fed into large language models, and the growing complexity of complaints is an early sign of it.
It was clear from the panel that there are no shortcuts in the market. Tomorrow’s leaders will combine solid fundamentals with a clearly chosen proposition, invest in data and operational excellence before the glossy extras, and keep enough flexibility in their organisations to respond to shocks they cannot yet name.