News
Keeping you up to date on news, events and what’s happening at ESG…

Keeping you up to date on news, events and what’s happening at ESG…
By Carolyn Burns, Head of Industry Change & Market Engagement, ESG Global
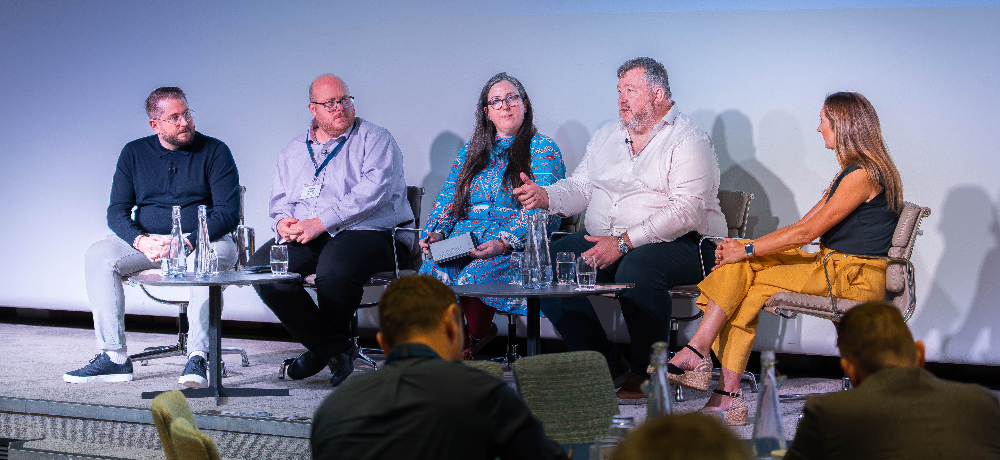
I recently chaired a panel at Smarter Energy Insights Forum, and I kicked things off by asking the room, full of industry experts, to stand up if they had a smart meter. Around 70% did, roughly in line with the national rollout.
But when I asked who had an energy smart appliance that could be turned up, down or off remotely, the numbers dropped sharply. Only a handful stood for solar panels, a battery, or a heat pump, with things only picking up when it came to electric vehicles.
It was a useful reminder, even for a room of people who live and breathe this industry, that the assets underpinning consumer-led flexibility are still relatively rare (barring electric vehicles) in most households, our own included.
That exercise set up the real question I wanted the panel to wrestle with: if the uptake of smart, flexibility-ready devices is so low in a room of energy experts, how are things fairing for the average consumer? And does that mean we’re designing the flexibility systems around the needs of the consumer, or are we asking them to navigate too much of the energy system’s complexity?
The answer, unsurprisingly, was somewhere in between, but the discussion that followed offered some genuinely useful insight for anyone thinking about how data, consent and interoperability will shape the next phase of retail energy.
We had representatives on stage from three distinct but closely related workstreams: the consumer consent solution, tariff interoperability, and the smart data repository. Each is tackling the same underlying challenge from a different angle, namely how to make energy data more accessible, more standardised and more trustworthy, without overwhelming the consumer or compromising their protection.
One of The Retail Energy Code Company’s (RECCo) representatives explained that the first minimal marketable product of the consumer consent solution is due in March 2027, focused initially on electricity consumption and half-hourly data.
The ambition, though, is much bigger: a single, reusable “one truth view” where a consumer can see every permission they’ve granted, who is accessing their data, and for what purpose.
The comparison drawn repeatedly throughout the session was with open banking. The idea isn’t to reinvent consumer trust from scratch, but to borrow a model people already recognise and feel reasonably comfortable with, so that switching, tariff comparison, flexibility services and asset control can all sit behind a familiar, consistent consent journey.
Importantly, once a consumer has created their identity within the solution, that credential is designed to be reusable across multiple providers (while still requiring consent for each provider) and use cases, reducing the repeated friction that exists today every time someone signs up to a new service.
This tariff interoperability project is being built in deliberate phases, starting with publicly mandated tariff information before integrating customer-specific tariff data and eventually expanding scope further. The project exists because third-party optimisers were having to build bespoke integrations with every supplier individually, just to access data that ought to be standardised and machine-readable in the first place.
Meanwhile, a longer, five-to-six-year programme for the Smart Data repository was outlined. It starts with market-wide half-hourly data becoming available by the end of this fiscal year, before broadening to include settlement and contract data.
There appears to be an enormous volume of creative use cases already emerging from stakeholders engaging with this data, well beyond anything the industry had originally anticipated.
Perhaps the liveliest part of the discussion came from our independent consultant panellist, who offered a genuinely useful counterpoint to the optimism elsewhere on stage.
The argument was straightforward but important: choice is a burden, and meaningful, informed consent at the level of detail these schemes require is, realistically, out of reach for most of the public. The oft-cited statistics that the majority of people want control of their energy data was questioned: does it really reflects what people want, versus wanting their data to simply be secure and well managed on their behalf.
Instead it was suggested that we should aim for genuine transparency and robust opt-out mechanisms, but we also need to get comfortable, as an industry, with opt-in by default for many of these services, rather than depending on consumers actively navigating permission structures they don’t have the context to evaluate.
This tension between designing for engaged early adopters and designing for the majority who simply want the lights to come on and their bills to be fair came up repeatedly.
One of the panellists put it plainly: for the vast majority of the market, flexibility participation has to be entirely passive. People aren’t going to take time out of their day to flick a switch or make a considered choice, however good the interface is.
If we want genuine scale, the aim has to be no decisions and no actions required from the consumer at all, with the benefit simply arriving.
We also spent time discussing where friction currently exists in these journeys, and there was a useful reframing offered here too. While policy and governance requirements can feel like obstacles, several panellists made the point that this kind of friction is often doing exactly what it should.
Personal energy data can be sensitive, and the checks and balances that slow things down are there precisely because this data could be misused by bad actors. The recent policy statement on potential licence changes to facilitate the smart data repository was welcomed on stage as a helpful firming up of the regulatory position, giving suppliers and platform teams more confidence in exactly where they need to get to.
On the data itself, there was reassurance that data availability is less of a barrier than it once was. Elexon’s load shaping service, drawing on all thirty million electricity meter points rather than the old, much smaller sample sizes used for legacy profiling, means that even where a consumer has opted out or where communication issues persist (a particular challenge in parts of the country still awaiting improved network coverage), highly accurate estimated data can fill the gap.
Some of the most thoughtful contributions from the floor concerned the practical realities of shared and rented accommodation, and of vulnerable consumers more broadly.
On HMOs and shared households, the consent solution’s approach allows an individual to give consent in their own right as a data subject, alongside emerging landlord-tenant models, though the panel was candid that most of the answers here are still being worked through in collaboration with the Information Commissioner’s Office and Ofgem.
There was also a valuable observation that assumptions about who occupies a property are shifting, with more adults living in shared accommodation for economic reasons, and a reminder that if we don’t build accessible pathways for people to participate, they will simply find their own routes around the rules regardless.
On vulnerability, there was strong consensus that a one-size-fits-all solution doesn’t exist, but real optimism about what’s possible when data is used well. Social housing providers, for example, are already exploring how consumption data could flag a vulnerable tenant who has stopped using their usual appliances, without needing to send someone round to check in physically.
Our independent consultant offered a sharper challenge here too, drawing a parallel with the price cap, which she argued has, if anything, entrenched consumer inertia by making the “safe” choice feel officially endorsed rather than genuinely optimal. The view was that we must protect people who are truly vulnerable, but resist scope creep that ends up diluting the benefits available to everyone else through a more dynamic, flexible market.
Non-domestic customers were rightly flagged as a group who can’t be left behind indefinitely, even though both the consent solution and tariff interoperability are, for now, focused on domestic customers and only the very largest non-domestic suppliers.
Both workstreams confirmed that expansion into the broader non-domestic market is firmly on the roadmap, guided by clear use cases and industry engagement rather than a single big-bang rollout.
If there’s one thread that ran through the whole session, it’s that none of this works without the smart meter estate continuing to function reliably, communicating consistently, and eventually being supported by connectivity beyond current 4G limitations. The ambition across these programmes is significant, but it all rests on that foundational infrastructure doing its job quietly in the background.